Business credit · CIBIL MSME Rank
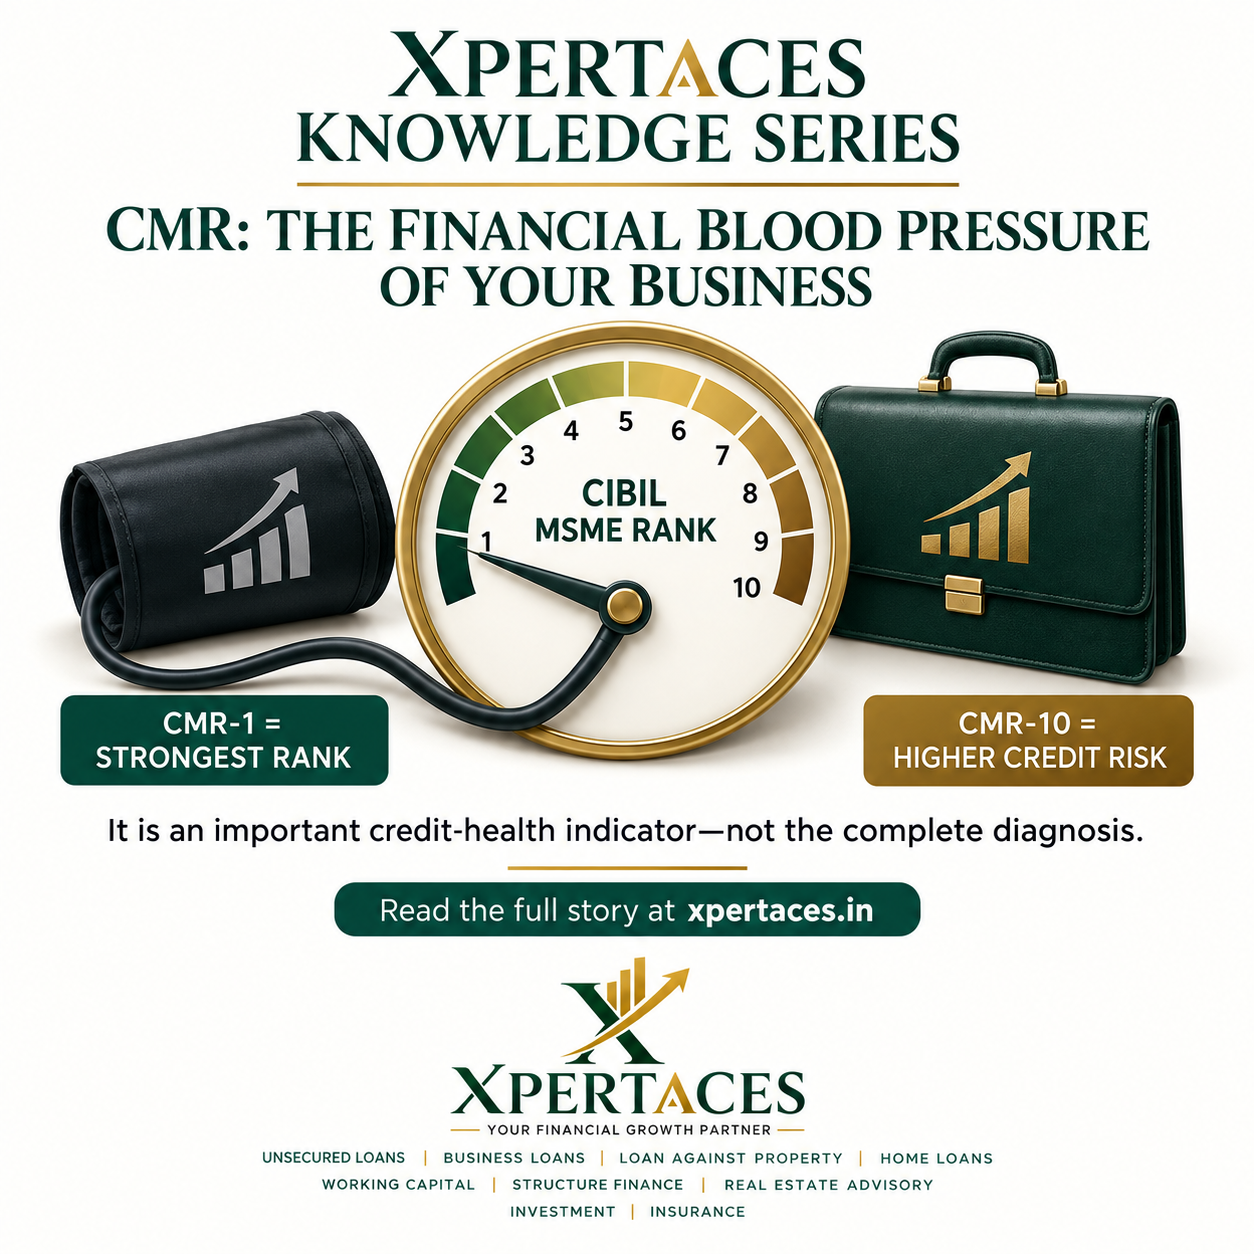
CMR: the financial blood pressure of your business
An important credit-health indicator can reveal financial stress before it becomes obvious. Here is CIBIL MSME Rank explained through a story every business owner can understand.
Meet Mr. Roy—and his apparently healthy business
Mr. Roy runs a successful manufacturing business. His factory is active, orders are coming in, employees are being paid and customers appear satisfied. From the outside, the business looks healthy.
One morning, he visits his doctor for a routine check-up. He feels perfectly fine, yet the doctor checks his blood pressure.
“Why check it when I have no symptoms?” Mr. Roy asks. The doctor replies, “Because blood pressure can reveal stress inside the body before the problem becomes visible outside.”
Your business’s CIBIL MSME Rank—commonly called CMR—works in a somewhat similar way. It can help a lender understand the credit behaviour inside a business that may look perfectly healthy from outside.
What exactly is CMR?
CIBIL MSME Rank is a commercial credit-risk indicator provided by TransUnion CIBIL for eligible business borrowers. It summarises information from the business’s Company Credit Report, or CCR, into a rank from CMR-1 to CMR-10.
Think of it like finishing first in a race: Rank 1 is the position a business would prefer. CMR availability depends on TransUnion CIBIL’s applicable eligibility criteria and the commercial credit information available for the business.
The CCR is the complete medical file
If CMR is the blood-pressure reading, the Company Credit Report is the detailed medical file. The CCR is created from commercial credit information reported by lending institutions and may contain working-capital facilities, term loans, equipment finance, secured facilities, outstanding balances, repayment history, overdue amounts and credit enquiries.
CMR summarises the risk into one rank. The CCR provides the details behind it. A doctor would not prescribe treatment after looking at only one reading; similarly, a responsible lender does not assess a business only from its CMR.
What can affect the CMR?
Repayment behaviour
Timely servicing demonstrates discipline. Delayed instalments, overdue interest, irregular accounts or defaults can weaken the commercial credit profile.
Credit utilisation
Continually using the entire working-capital limit—or exceeding it—may indicate liquidity pressure. Prudent utilisation generally presents a healthier picture.
Borrowing pattern
The nature, number and conduct of existing facilities help lenders understand how the business manages borrowed funds.
Recent enquiries
Repeated applications across lenders can become part of the business’s commercial credit story and warrant further examination.
Mr. Roy asks for more working capital
Mr. Roy approaches a bank to enhance his cash-credit limit so his growing company can purchase more raw material. The banker reviews the CMR and CCR—but also examines audited financial statements, turnover, profitability, GST returns, bank conduct, debtors, creditors, existing obligations, working-capital cycle, proposed use of funds, available security and the promoters’ credit profiles.
A strong CMR can create a positive first impression and help the proposal progress to detailed assessment. It cannot guarantee sanction. Declining turnover, insufficient cash flow, excessive debt, weak banking conduct or an unsupported requirement can still create difficulties.
A weaker CMR may lead the lender to seek explanations, examine account conduct more closely, reduce exposure, request additional comfort, impose stricter conditions or decline the proposal under its policy.
CMR influences the lending conversation. It does not decide the entire outcome by itself.
CMR is not the promoter’s personal CIBIL score
A personal CIBIL score relates to an individual—such as a proprietor, partner, director or guarantor—and generally runs from 300 to 900, where a higher score is usually stronger. CMR relates to an eligible business entity and runs from 1 to 10, where a rank closer to 1 is stronger.
For a business loan, lenders may examine both the company’s commercial credit profile and the personal credit histories of its promoters or guarantors. A healthy company profile does not erase problems in a promoter’s personal report, and an excellent personal score does not compensate for serious irregularities in company borrowings.
What a strong CMR does—and does not—mean
Support credibility
It can create a stronger first impression, demonstrate responsible credit conduct and help an eligible proposal progress more efficiently.
Guarantee sanction
It cannot guarantee approval, amount, pricing or unsecured funding, nor replace financial statements, repayment capacity and lender policy.
How a business can maintain healthier credit conduct
- Pay loan instalments and interest on time.
- Use working-capital limits prudently and avoid persistent excess drawings.
- Monitor account conduct and unexplained cheque returns.
- Submit renewal documents, statements and information on time.
- Apply for credit selectively instead of approaching many lenders without a strategy.
- Review the Company Credit Report periodically for accuracy.
- Raise formal disputes for genuine reporting errors.
- Communicate temporary financial stress to lenders early and transparently.
If information is accurate, improvement generally comes from consistent corrective behaviour—not an instant “rank repair.”
Do not wait for a financial emergency
Most people do not want to discover high blood pressure during a medical emergency. A business should likewise avoid discovering commercial-credit problems only after submitting an urgent application.
Before seeking a working-capital enhancement, term loan, Loan Against Property or structured facility, understand the business’s CMR, review the CCR, assess current utilisation and obligations, identify overdue or disputed accounts and check whether promoter credit profiles are satisfactory.
The simplest way to remember CMR
At the end of Mr. Roy’s appointment, the doctor explains: “Your blood pressure is an important health indicator. It does not tell me everything about your body, but it tells me where I may need to look more carefully.”
CMR is a financial-health indicator for an eligible business borrower: it summarises commercial credit risk on a scale of 1 to 10, where 1 is the strongest rank, and helps lenders decide how confidently and closely they should examine the business.
Your business may look healthy from the outside. CMR helps lenders understand how its borrowing behaviour looks from the inside.
Sources and disclaimer
This article is for financial education. CMR availability, eligibility, pricing, security and approval remain subject to TransUnion CIBIL’s criteria and each lender’s independent policy. TransUnion CIBIL does not sanction or reject loans.
CIBIL Rank and Company Credit Report FAQs ↗
CIBIL: Good credit habits for a business ↗