Credit fundamentals · Individual borrowers
What does your CIBIL score tell a lender?
It is an important snapshot of credit behaviour—but it is neither the entire credit report nor a guaranteed approval or rejection.
First, what is a CIBIL score?
A CIBIL score is a three-digit summary of an individual’s credit history. It is generated from information in the Accounts and Enquiries sections of the CIBIL credit report, including borrowing, repayment behaviour, outstanding balances and recent credit applications.
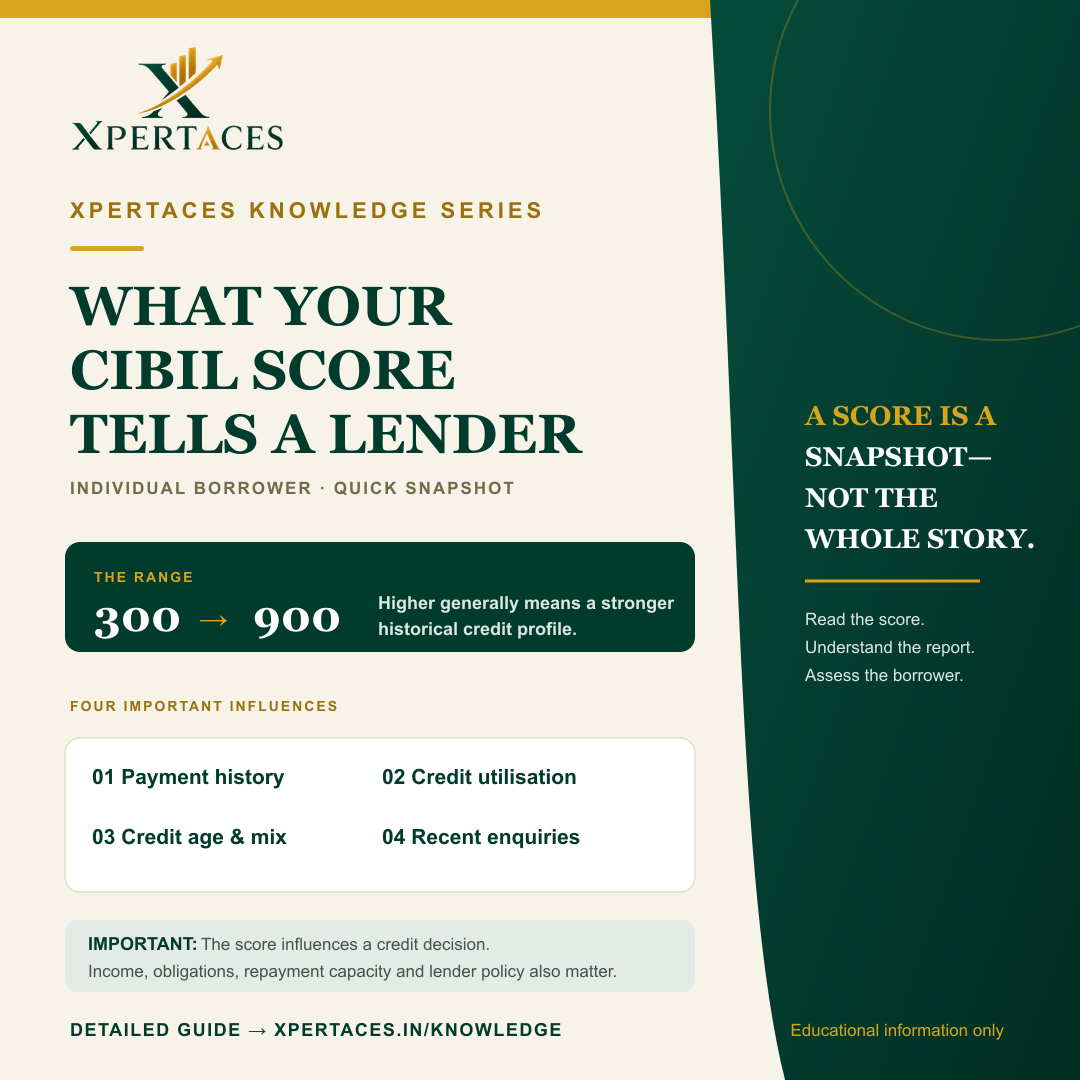
The score ranges from 300 to 900. A higher score generally indicates stronger historical credit behaviour and may improve the likelihood of a favourable assessment. It does not, by itself, create an entitlement to a loan.
The score and the report are not the same
The score is the headline number. The credit report is the detailed record behind it. A lender may review open and closed loan accounts, credit-card limits and balances, repayment history, overdue amounts, enquiries and the borrower’s role in joint, co-borrowed or guaranteed facilities.
That is why two applicants with the same score may still receive different outcomes: the composition and recent behaviour inside their reports can be different.
Four important influences
Payment history
Late payments, overdue EMIs and defaults can negatively affect the score and raise questions about repayment discipline.
Credit utilisation
Consistently using a high proportion of available revolving credit may indicate greater dependence on borrowed funds.
Credit age and mix
The length of credit history and the balance between secured and unsecured borrowing contribute to the overall profile.
Recent enquiries
Multiple applications within a short period may indicate active credit seeking and can influence the assessment.
What does NH or NA mean?
A new-to-credit borrower may not have enough credit history to generate a score and can receive an NH or NA result. This is not automatically a “bad” result. It usually means the lender must rely more heavily on income, banking behaviour, stability, obligations, security and its own underwriting rules.
What else does a lender consider?
A lender normally assesses the complete borrower profile. Depending on the product, this can include income stability, business or employment continuity, existing monthly obligations, repayment capacity, banking conduct, loan purpose, borrower age, security or property, documentation and the lender’s prevailing credit policy.
A strong score can support an application, but it does not replace adequate income, repayment capacity, complete documents or product eligibility.
Healthy credit habits
- Pay EMIs and credit-card dues on time.
- Use available credit prudently and avoid repeatedly reaching limits.
- Apply for new credit selectively rather than making several simultaneous applications.
- Maintain a sensible mix of secured and unsecured borrowing where appropriate.
- Review the credit report periodically and raise a dispute if genuine inaccuracies appear.
- Monitor joint, co-borrowed and guaranteed accounts because missed payments can affect every liable borrower.
For channel partners
Do not treat the score as the entire case. Read the report, understand the reasons behind the number and discuss the borrower’s income, obligations and requirement before recommending a financing route. A thoughtful initial assessment saves time for the borrower, the partner and the lender.
Source and disclaimer
This educational guide is based on consumer guidance published by TransUnion CIBIL. It is general information, not credit, legal or financial advice. Credit eligibility, pricing, terms and approval remain subject to the lender’s independent assessment and prevailing policies.