Funding Readiness Series · Part 1
How much funding does your business actually need?
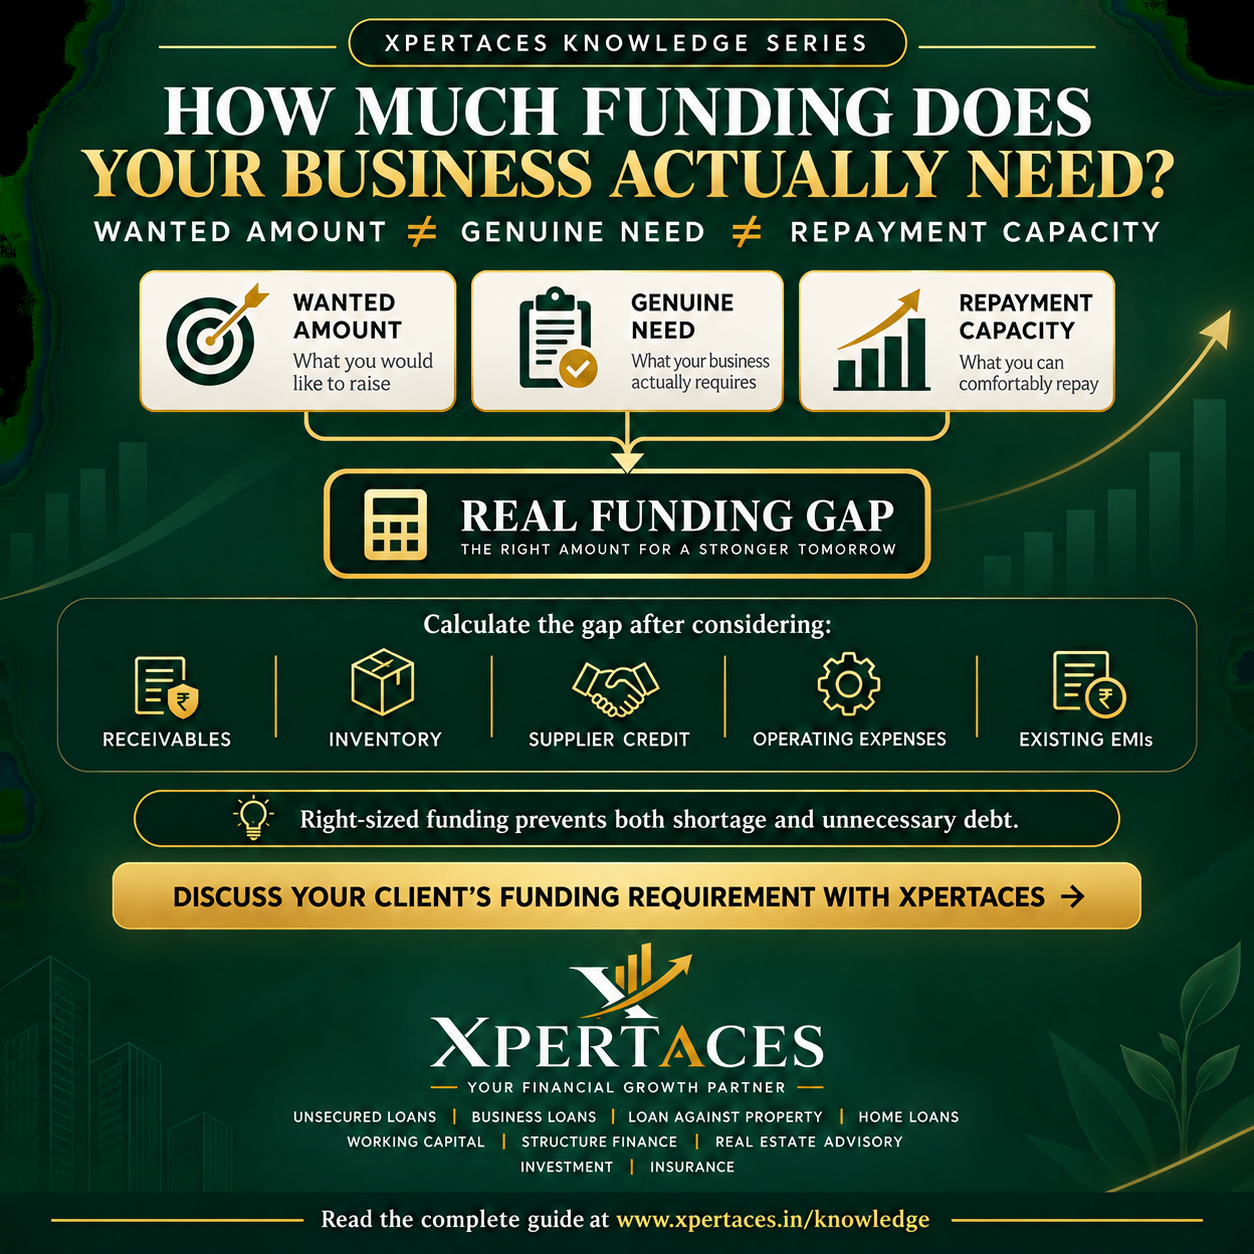
The amount a business wants, the amount it genuinely needs and the amount it can comfortably repay may be three different numbers. The right proposal begins by reconciling all three.
Calculate the genuine gap before choosing the loan.
₹2 crore may be the request—but is it the requirement?
Business owners commonly begin with a round number: “We need ₹2 crore.” That figure may come from an immediate payment pressure, an expansion plan or simply the maximum facility they hope to obtain.
A sound funding assessment begins one step earlier. It asks what the money will do, when it will be used, how long it will remain tied up and which future cash flow will repay it.
Wanted amount is what the business would like to raise. Genuine need is the properly calculated gap. Repayment capacity is what future cash flow can safely support.
First identify the purpose
Working capital
Finance for inventory, receivables and day-to-day operations after considering supplier credit and the business’s own contribution.
Asset or project funding
Finance for machinery, property, fit-outs or expansion, structured around project cost, promoter contribution and the asset’s useful life.
Seasonal requirement
A short-duration gap caused by peak inventory, a large order, delayed collections or a predictable seasonal cycle.
Debt realignment
Replacing costly or mismatched debt with a more suitable structure, subject to total cost, conditions and repayment capacity.
A short-term cash-credit facility should not normally fund a long-life asset. Equally, a long-tenure term loan may be inefficient for a temporary operating-cycle gap. The duration of the facility should broadly match the duration of the need.
A practical working-capital framework
Working capital becomes necessary because cash leaves the business before customer collections arrive. The gap is influenced by the length of the operating cycle—not only by annual turnover.
Inventory + eligible receivables + minimum operating cash, less supplier credit and other normal operating liabilities, indicates the operating gap. Available internal funds and the promoter’s contribution must then be considered before arriving at the external funding requirement.
This is a management framework, not a guaranteed bank formula. Lenders may use turnover, cash-budget, drawing-power or other appraisal methods under their policies. RBI guidance asks banks to appraise the genuine working-capital requirement with the borrower’s business cycle and short-term credit needs in mind.
Eight numbers that should be on the worksheet
- Expected monthly sales and how much of it is on credit.
- Collection period for receivables—including habitual delays.
- Inventory holding period for raw materials, work-in-progress and finished goods.
- Supplier credit period actually available, not merely requested.
- Monthly operating expenses such as salaries, rent, utilities and statutory payments.
- Existing limits and loans, including EMIs, interest and upcoming repayments.
- Internal funds available without disturbing essential business reserves.
- Peak or contingency requirement supported by a realistic reason and duration.
The calculation should use realistic assumptions supported by financial statements, GST data, bank transactions, ageing reports, orders and cash-flow projections.
For machinery or expansion, calculate the complete project cost
The invoice value is rarely the entire requirement. A project budget may also include installation, freight, duties, civil work, professional fees, deposits, contingency and the additional working capital needed after operations expand.
The external requirement is broadly the complete project cost less the promoter contribution, available internal accruals and any confirmed support. The repayment schedule should then be tested against the incremental cash flow expected from the investment.
Funding the machine but overlooking the inventory, receivables and operating expenses needed to run the increased capacity can leave a technically completed project short of cash.
Why under-borrowing can be expensive
- Suppliers may remain unpaid or withdraw credit.
- Production may slow because inventory cannot be replenished.
- Expensive emergency borrowing may fill the remaining gap.
- EMIs may begin before the project has enough cash to service them.
- The business may repeatedly seek enhancements, losing time and credibility.
A modest buffer for a demonstrable timing or seasonal risk can be sensible. An unexplained cushion added to a round-number request is not the same thing.
Why over-borrowing is not a sign of strength
- Interest and fees are incurred on money the business may not need.
- Additional collateral or guarantees may be committed unnecessarily.
- Higher obligations reduce headroom for future borrowing.
- Surplus funds can be diverted into unrelated or low-return uses.
- A larger sanction may carry tighter conditions and monitoring.
The objective is not the highest possible loan. It is sufficient, suitably structured capital that the business can use productively and repay comfortably.
Requirement is not the same as eligibility
A correctly calculated gap does not automatically become the sanctioned amount. A lender will independently assess financial performance, banking conduct, credit history, leverage, security, promoter contribution, business risk and repayment capacity.
If the genuine need exceeds comfortable repayment capacity, the answer may involve phasing the project, increasing promoter contribution, improving collections, reducing inventory, negotiating better supplier terms or using a different mix of facilities—not simply applying to more lenders.
The Xpertaces viewpoint
Funding should be treated as a financial structure, not a number entered in an application form. Xpertaces and its channel partners begin by understanding the business purpose, mapping the cash cycle, calculating the gap and testing repayment capacity before matching the case with a suitable facility and lender.
Good funding supports the business cycle. It should not create the next cash-flow problem.
Your pre-funding checklist
- State the purpose in one clear sentence.
- Separate recurring working capital from long-term asset funding.
- Prepare receivable and inventory ageing.
- Map supplier credit and monthly operating outflows.
- List every existing facility and repayment.
- Build a realistic month-wise cash-flow projection.
- Identify internal contribution and security available.
- Stress-test whether repayment remains comfortable if sales or collections are slower than expected.
Reference and disclaimer
This article is general educational information. It is not a sanction promise or a substitute for a case-specific financial assessment. Actual eligibility, assessment method, facility structure, pricing and approval remain subject to the lender’s prevailing policy and independent credit decision.