Business finance · Advisory & execution
Why every business needs a financial expert in its funding journey
A business owner usually knows why money is needed. A financial expert helps determine how much is appropriate, which facility fits, how the proposal should be presented and where it should be placed.
Begin with the requirement—not a random lender application.
A funding requirement is not merely a loan application
Suppose a growing business needs ₹2 crore. The owner may immediately ask, “Which bank will give me the loan?” But that may not be the first question.
The right questions are: Why does the business need the money? How was ₹2 crore calculated? Is the need temporary or long term? Will the money purchase machinery, support receivables, build inventory, refinance expensive debt or fund expansion? Which cash flow will repay it?
The answers determine whether the business needs cash credit, overdraft, a working-capital term loan, bill discounting, a machinery loan, Loan Against Property, unsecured finance or a structured combination.
A financial expert helps turn “I need money” into a clearly defined, appropriately sized and repayable funding requirement.
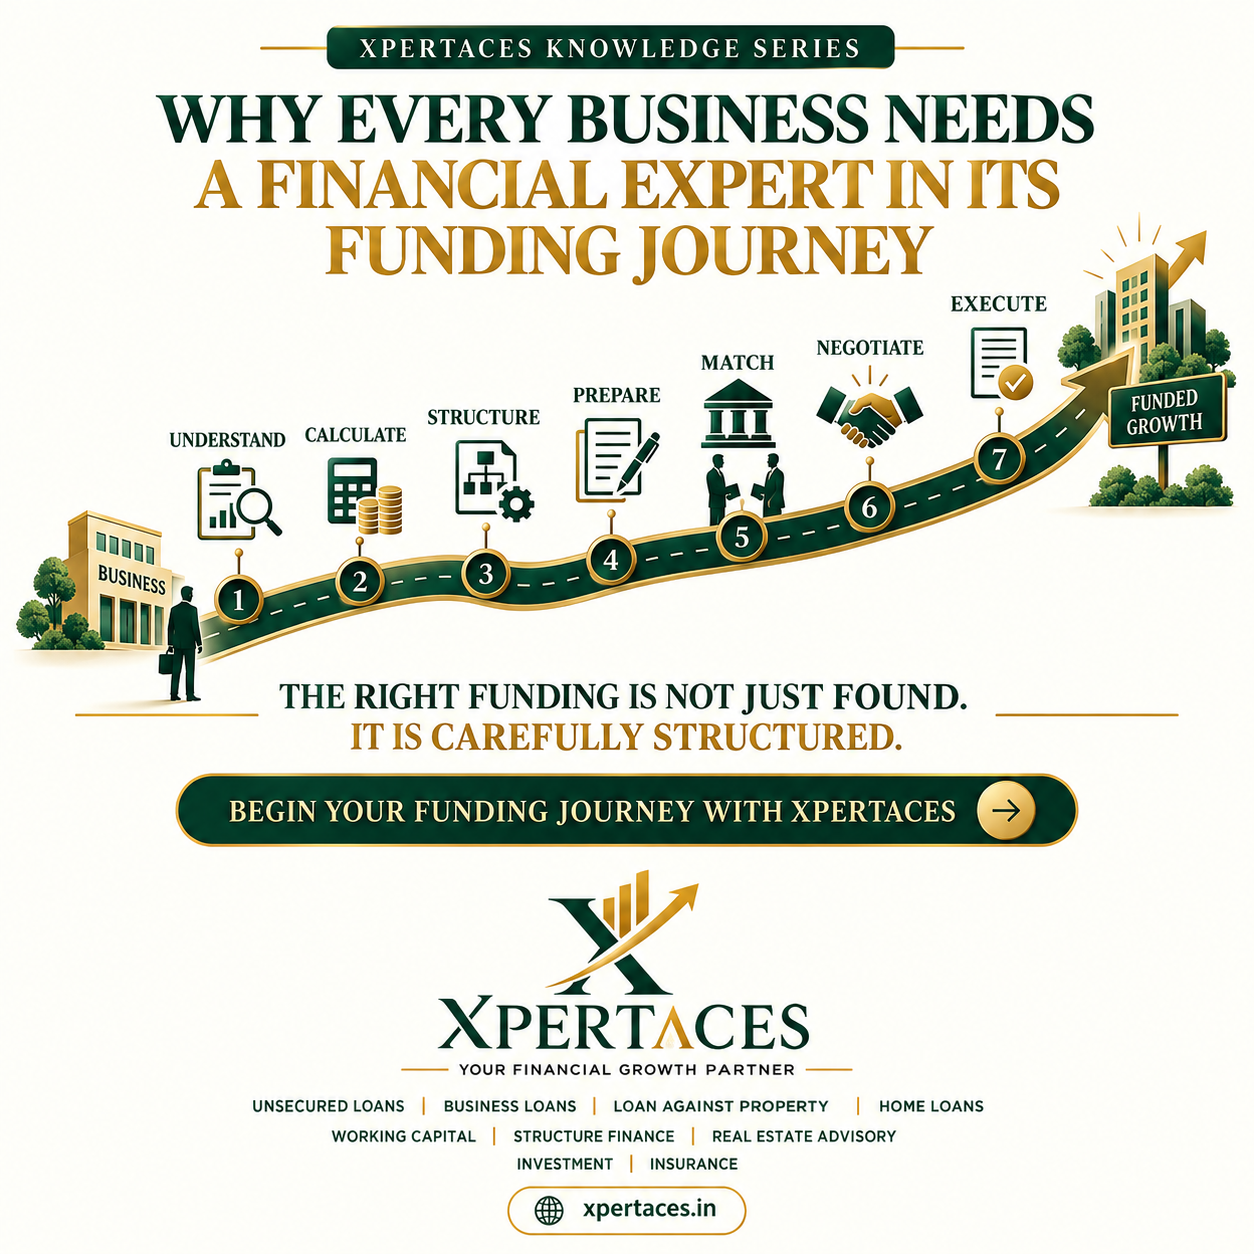
The seven stages of a well-managed funding journey
Understand
Study the business model, borrowing purpose, operating cycle, existing debt, security position, timing and expected repayment source.
Calculate
Estimate the genuine funding gap using financial statements, cash flows, receivables, inventory, supplier credit, project cost and promoter contribution.
Structure
Choose an appropriate mix of working capital, term finance, secured or unsecured facilities, tenure, moratorium and repayment pattern.
Prepare
Organise documents and present a coherent credit story covering performance, purpose, risks, mitigants, repayment capacity and projections.
Match
Identify lenders whose programme, risk appetite, geography, sector preference and security norms align with the borrower’s profile.
Negotiate
Compare not only interest rates, but also fees, margin, collateral, covenants, renewal conditions, guarantees and disbursement requirements.
Execute
Coordinate credit queries, sanction conditions, valuation, legal review, documentation, security creation and final disbursement.
1. Understanding the real requirement
A borrower’s initial estimate is often based on immediate pressure rather than a complete calculation. A business may ask for additional working capital when the real issue is slow collection, excess inventory or a mismatch between customer and supplier credit periods.
Another business may request a short-term overdraft for machinery that will generate returns over several years. This creates repayment pressure because the facility does not match the life of the asset.
An expert examines the reason, amount and timing before recommending a product. Sometimes the most valuable advice is to restructure the requirement—not increase the borrowing.
2. Calculating how much the business can responsibly borrow
The desired loan amount and the eligible loan amount are not always the same. Lenders assess turnover, profitability, cash generation, existing obligations, banking conduct, promoter contribution and available security.
A credible calculation should answer two separate questions:
- How much does the business genuinely need?
- How much can the business reasonably service?
A proposal that ignores either question can become unsuitable even if it is sanctioned.
3. Selecting the right facility
Different funding needs require different instruments. Working capital should generally support operating-cycle gaps. A term loan should normally fund assets or projects that generate benefits over time. Bill discounting may suit receivables from acceptable customers. Loan Against Property may provide longer-tenure secured finance, while an unsecured facility may address a smaller requirement where speed and flexibility justify the cost.
The cheapest-looking product is not necessarily the most suitable. Tenure, repayment pattern, security, flexibility and total cost must align with the purpose.
4. Preparing a lender-ready credit story
A lender does not evaluate documents in isolation. It evaluates the story connecting the business, its financial performance, the proposed facility and the repayment source.
A well-prepared proposal explains:
- What the business does and how it earns
- Why funding is required now
- How the amount was determined
- How the facility will improve operations or growth
- Which cash flow will service the debt
- What risks exist and how they are managed
- What security or promoter support is available
Preparation does not mean hiding weaknesses. It means identifying them, explaining them truthfully and presenting appropriate mitigants.
5. Matching the case with the right lender
Every lender has a different credit appetite. One may be comfortable with a particular industry, property type, turnover range or geographic market while another is not. Some programmes are designed for secured MSME lending; others focus on cash-flow-based or programme-driven facilities.
Submitting the proposal everywhere is rarely a strategy. It can generate unnecessary enquiries, inconsistent information and borrower fatigue. Expert lender matching begins with the case—not with whichever lender happens to respond first.
6. Comparing the complete sanction—not just the rate
A loan with a slightly lower interest rate may carry a higher margin, shorter tenure, stricter collateral requirement or difficult renewal conditions. Businesses should examine the entire commercial and operational structure.
Financial terms
Rate, benchmark, spread, fees, penal charges, margin, repayment schedule and prepayment provisions.
Risk commitments
Collateral, personal guarantees, corporate guarantees, insurance and security-creation obligations.
Covenants
Financial ratios, information requirements, restrictions, renewal terms and events of default.
Disbursement conditions
Documentation, approvals, valuation, legal clearance, promoter contribution and pre-disbursement compliance.
RBI’s fair-practices framework emphasises transparent disclosure of fees, charges and material lending terms so borrowers can make informed comparisons. An advisor helps the borrower interpret what those terms mean for the business in practice.
7. Why sanction is not the end of the journey
A sanction letter is an approval subject to conditions; it is not money in the account. Property-backed cases may require title review, valuation, mortgage creation and insurance. Business facilities may require updated statements, documentation, account closure, pari-passu arrangements or proof of promoter contribution.
Unmanaged conditions can delay or even prevent disbursement. Disciplined follow-through is therefore as important as obtaining the initial sanction.
What a good financial expert should—and should not—do
Create clarity
Explain the process, identify risks, recommend suitable options and communicate realistic expectations.
Protect accuracy
Use truthful information, consistent submissions and complete disclosure of material facts.
Promise approval
No advisor controls a lender’s independent credit decision, pricing or final terms.
Manufacture eligibility
Documents, turnover, income, valuations or borrower information must never be misrepresented.
The channel partner and Xpertaces: one coordinated journey
A Chartered Accountant, DSA, loan advisor, consultant, real-estate professional or other trusted intermediary may understand the client relationship long before a funding requirement reaches a lender.
The channel partner brings trust, context and ongoing client understanding. Xpertaces can add financial structuring, lender alignment, credit coordination and execution support behind that relationship.
The channel partner retains the client relationship. Xpertaces works as the specialist execution team—helping the partner offer a wider capability without being replaced in front of the client.
Questions to answer before approaching a lender
- What is the exact purpose of the funding?
- How has the required amount been calculated?
- Is the need short term, recurring or long term?
- Which cash flow will repay the facility?
- What existing debt and monthly obligations must be serviced?
- What security and promoter contribution are available?
- Are the financial statements, GST returns, bank statements and credit reports ready?
- Which product and lender policy best fit the complete profile?
The final takeaway
A financial expert cannot turn an ineligible case into an eligible one, control a lender’s decision or guarantee a sanction. The real value lies elsewhere: defining the need correctly, preventing avoidable mistakes, presenting the case coherently, comparing terms responsibly and coordinating the journey to its most appropriate outcome.
A business loan is not merely found. The right funding pathway is understood, calculated, structured, prepared, matched, negotiated and executed.
Reference and disclaimer
This article is general educational information, not a promise of finance or professional advice for any specific borrower. Eligibility, pricing, terms and approval remain subject to each lender’s independent assessment and prevailing policy.