Funding Readiness Series · Part 3
The right loan is more than a low interest rate
Two funding offers can quote similar rates and still have very different consequences for cash flow, flexibility and risk. Compare the whole structure before deciding.
Look at what the business must pay, pledge and comply with.
The lowest quoted rate may not be the best fit
A business owner naturally asks, “What is the interest rate?” The answer matters. But a rate alone does not tell you when the money can be drawn, how it must be repaid, what charges apply, what security is committed or what conditions must be met before disbursement.
Consider a business purchasing machinery while also needing cash to buy more raw material. A competitively priced term loan may fund the machine but leave the operating-cycle gap untouched. A cash-credit line may help with inventory and receivables but be unsuitable for a long-life machine. The right answer may be a carefully sized combination, if the lender accepts the case.
Does the facility’s purpose, amount, availability and repayment pattern match the business’s actual cash cycle?
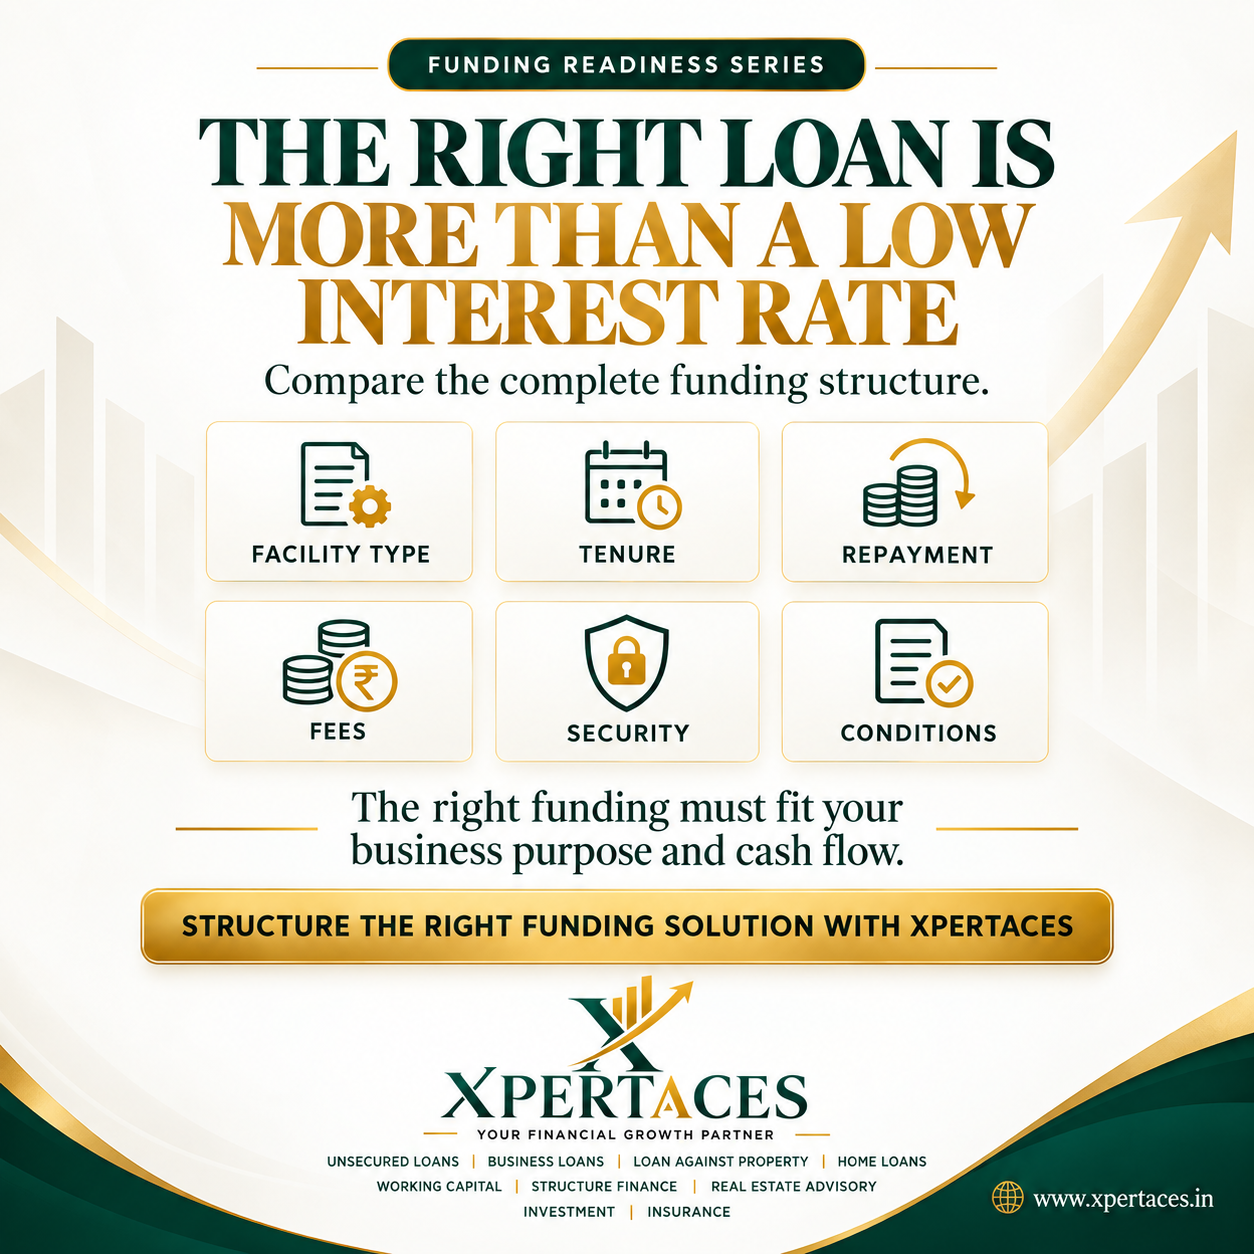
Six factors to compare
What kind of finance?
Term loan, cash credit, overdraft, bill discounting, loan against property or a combination: each serves a different funding need.
For how long?
Match a long-term asset with a suitable repayment period and a short-term operating gap with appropriate revolving or short-duration finance.
When does cash leave?
Compare EMI timing, instalment size, moratorium if offered, renewal and clean-up requirements against realistic monthly cash flow.
What is the full cost?
Review interest, processing and other disclosed charges, valuation or legal costs, insurance, prepayment terms and applicable penal charges.
What is committed?
Consider collateral, margin, promoter contribution, guarantees, insurance and the effect on capacity for future borrowing.
What must be maintained?
Understand financial covenants, reporting, stock statements, renewal tests, restrictions and conditions before disbursement.
Start with the facility type
Working capital is tied to the operating cycle: inventory is purchased, goods or services are sold, receivables are created and customers pay. A cash-credit or other suitable revolving structure may allow the business to draw and repay as that cycle moves, subject to the lender’s rules and drawing power.
A term loan usually finances a defined asset or project and is repaid over an agreed period. Bill discounting can release cash against eligible invoices. Loan Against Property may provide secured funding with a different tenure and security profile. An unsecured facility may be faster or more flexible for some cases but should still be assessed for total cost and repayment pressure.
Before comparing quotations, ask whether each product actually solves the same requirement. Our first guide shows how to calculate that requirement.
Test the repayment against the cash calendar
A business can be profitable over a year and still have lean months. A repayment schedule must work in those months too. Compare when principal begins, how often instalments fall due and whether a projected cash surplus remains after taxes, suppliers, salaries and existing debt service.
For a seasonal business, a lower rate coupled with an inflexible monthly schedule could be harder to manage than a slightly higher-cost structure aligned with collections. The right conclusion depends on the actual terms and a realistic forecast; it cannot be inferred from the rate alone.
Would the business still service the facility if collections arrive later than planned or sales are below the forecast? If not, revisit the amount, promoter contribution, tenure or facility mix.
Compare the all-in cost, not only the headline rate
Request the lender’s written schedule of charges and key terms. Look at whether the interest rate is fixed or floating, what benchmark and spread apply, when rates reset, and how interest is calculated. Then consider disclosed processing and other charges, security-related costs and any conditions attached to prepayment or closure.
RBI’s published guidance on key facts and fair practices explains why important terms and the all-in cost should be understandable to borrowers. The practical step is to obtain the actual written terms for the specific facility and read them together.
A slightly lower rate can be outweighed by higher one-time costs, a larger margin requirement or a shorter repayment period. Conversely, paying a higher rate is not automatically justified by greater flexibility. Quantify the trade-offs for the case at hand.
Understand what the business gives in return
Collateral is not free simply because it is already owned. Pledging a property, offering personal guarantees or committing a large margin changes the business’s risk and may restrict its ability to raise future finance. Check which assets are charged, whose guarantees are required and how the security is released or substituted.
Read the covenants as operational obligations. Examples may include maintaining specified ratios, furnishing periodic statements, routing business through an account, obtaining consent before new debt, or meeting renewal conditions. Their importance varies by facility and lender.
Finally, list every condition before disbursement. A sanction can still be delayed if legal review, valuation, security creation, approvals or promoter contribution are incomplete.
A simple two-offer comparison
Suppose two lenders offer the same loan amount for the same business purpose. Offer A quotes a lower rate but requires a larger promoter margin, a shorter repayment period and more collateral. Offer B quotes a somewhat higher rate but allows a repayment profile that better follows the cash generated by the project.
Which is better? There is no universal answer. Calculate the total disclosed cost, test monthly cash flow under each schedule and assess the value of the additional security or cash contribution. If Offer A’s lower rate causes a recurring cash squeeze, its apparent saving may not help the business. If the business has ample cash and accepts the security, Offer A may still be preferable. The decision requires the complete terms.
Questions to ask before accepting a sanction
- Does the sanctioned facility cover the actual use of funds and the required timing?
- What is the complete amount the business will pay, including disclosed fees and charges?
- When do interest and principal payments begin, and how do they compare with the cash forecast?
- What margin, collateral and guarantees are required?
- What documents and actions are needed before the first disbursement?
- What reporting, covenants and renewal conditions will apply afterward?
- What happens if rates change or the business wants to prepay, restructure or enhance the facility?
Where a term is unclear, ask the lender for a written explanation before signing. Keep the final sanction and charge schedule alongside the business’s own comparison.
The Xpertaces viewpoint
The funding decision begins with the business, not the lender’s rate card. Xpertaces and its channel partners can help define the requirement, prepare a lender-ready proposal, compare suitable structures and coordinate the route from sanction to disbursement.
The channel partner keeps the client relationship. Xpertaces contributes structuring, lender alignment and execution support so that the proposed facility can be evaluated against the client’s purpose and cash flow.
First, calculate the genuine need. Second, present a clear credit case. Third, compare the complete funding structure. These three decisions form the foundation of a responsible funding journey.
Reference and disclaimer
This article is general educational information. Product availability, costs, security, conditions and credit decisions depend on the lender and borrower. Xpertaces does not guarantee approval or particular terms.
Reserve Bank of India: Key Facts Statement and all-in cost overview